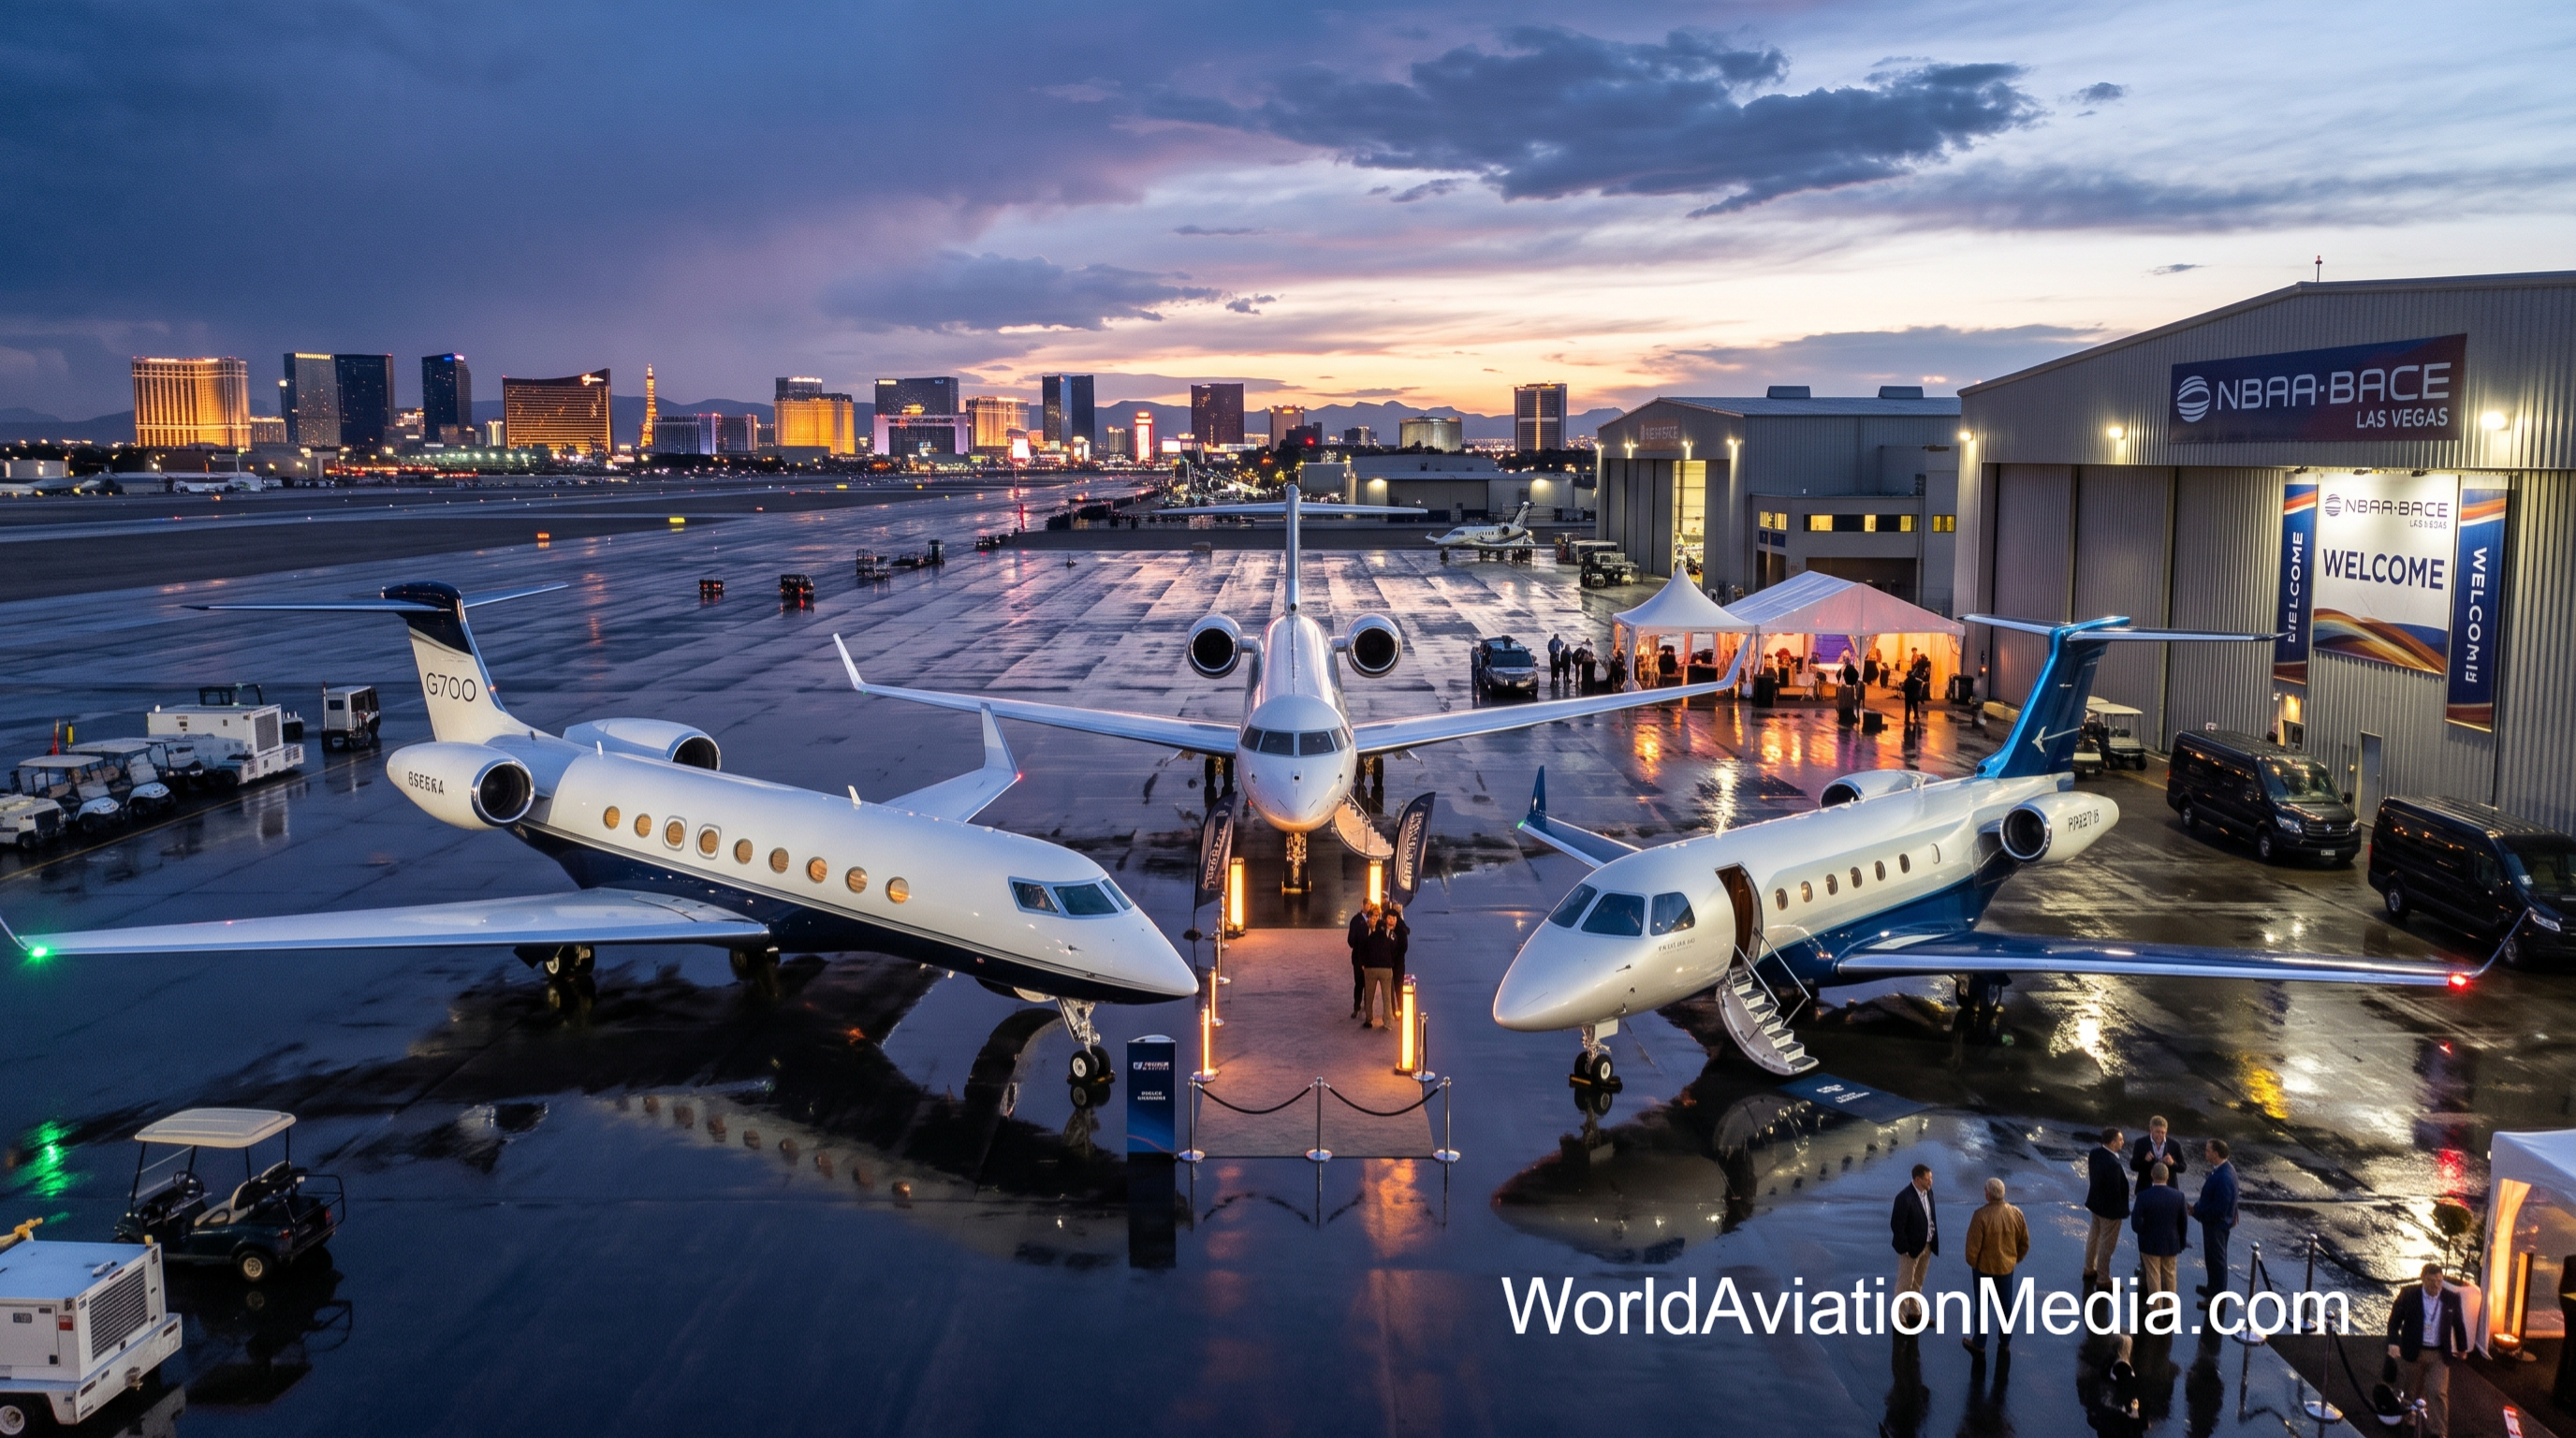
The $33 Billion BizJet Fortress: Can Gulfstream and Embraer Ramp Production Without Breaking the Supply Chain?
Key Takeaways
A $33+ Billion Combined Backlog: Entering NBAA-BACE 2026, Gulfstream Aerospace holds a massive $25 billion order backlog, while Embraer Executive Jets has surged to a record $8.2 billion backlog—forming a $33.2 billion demand fortress before even counting Bombardier and Textron.
Gulfstream’s 200-Jet Target: Powered by the entry into service of the ultra-long-range G700 and newly certified G800 alongside the G400/G500/G600 family, Gulfstream is scaling manufacturing in Savannah toward a historic 200-aircraft annual delivery rate.
Embraer’s Super-Midsize Stranglehold: Embraer’s $8.2 billion executive backlog is anchored by fleet orders and corporate demand for the Phenom 300E and Praetor 500/600 series, maintaining a book-to-bill ratio comfortably above 1.3x.
Bombardier’s $270M U.S. Footprint Expansion: Rather than chasing risky overproduction, Bombardier is fortifying high-margin aftermarket MRO, defense modifications, and U.S. industrial infrastructure through a $270 million U.S. footprint investment, ensuring supply chain stability supports its Global 7500/8000 flagship transition.
Inside Business Aviation’s Post-Cycle Era: Why Backlogs Refused to Normalize
Three years ago, Wall Street aerospace analysts predicted that the post-2021 boom in private jet demand would inevitably cool as interest rates rose and corporate flight departments digested deliveries. Instead, data presented surrounding the October 2026 NBAA-BACE convention in Las Vegas reveals that the top tier of business aviation has constructed an unprecedented financial moat.
How large is the current business jet order backlog in 2026? Combined, Gulfstream Aerospace ($25 billion backlog as of mid-2026) and Embraer Executive Jets (a record $8.2 billion backlog) hold more than $33.2 billion in firm aircraft orders. When combined with Bombardier’s multi-billion-dollar backlog and Textron Aviation’s Citation Gen3 pipeline, industry-wide business jet order books stretch two to three years forward, insulating OEMs against short-term macroeconomic volatility.
What is driving this sustained demand?
Fractional Fleet Megadeals: Operators like NetJets, Flexjet, and VistaJet have shifted from opportunistic spot buying to multi-year, multi-billion-dollar framework agreements to satisfy structurally higher fractional share ownership.
Ultra-Long-Range generational Replacement: Fortune 500 flight departments and ultra-high-net-worth principals are replacing 15-year-old Gulfstream G550s and Bombardier Global 6000s with clean-sheet flagships capable of Mach 0.90+ cruise, lower cabin altitudes (under 3,000 feet), and non-stop 7,500–8,000 nm city pairs.
Supply Chain Gating: Paradoxically, supply chain bottlenecks over the past 36 months prevented OEMs from over-delivering during peak order intake, turning potential boom-and-bust cyclicality into a multi-year plateau.
Gulfstream’s March Toward 200 Deliveries a Year
For General Dynamics subsidiary Gulfstream Aerospace, 2026 marks the transition from intensive flight-test certification spending to high-volume factory execution. With its $25 billion backlog anchored by the flagship G700 and ultra-long-range G800—alongside steady demand for the super-midsize G280 and large-cabin G500/G600—Gulfstream leadership has set its sights on scaling production toward 200 business jet deliveries per year.
To appreciate the magnitude of a 200-unit annual run rate at Gulfstream, consider the average selling price (ASP) of its product mix. Unlike light-jet manufacturers whose volume is weighted toward 6M–12M aircraft, Gulfstream’s backlog is heavily concentrated in $50M to $80M+ large-cabin and ultra-long-range jets. Delivering 200 Gulfstreams annually represents a revenue engine approaching $12 billion to $14 billion per year from a single division.
Achieving that rate without triggering completion-center delays requires synchronized execution across three manufacturing pillars:
Digital Thread Wing & Fuselage Assembly: Automated robotic drilling and laser alignment in Savannah, Georgia, have slashed structural assembly hours on the shared G700/G800 fuselage barrel and supercritical wing.
In-House Completions Expansion: During the initial G700 ramp, customized interior completions proved a major bottleneck as bespoke veneer, seating, and cabin management certifications slowed customer handovers. Gulfstream’s expanded completions centers in Savannah, Appleton (Wisconsin), and St. Louis are standardizing modular cabin architectures to cut completion cycle times by 20%.
Propulsion Synchronization: Close coordination with Rolls-Royce on the Pearl 700 engine and Pratt & Whitney Canada on the PW800 series ensures that powerplants arrive on the Savannah dock in lockstep with fuselage joins.
Embraer’s $8.2 Billion Executive Jet Juggernaut
While Gulfstream commands the ultra-long-range apex, Brazilian aerospace giant Embraer has built an unassailable fortress in the light and midsize/super-midsize segments. Swelling to a record $8.2 billion executive aviation backlog in 2026, Embraer has transformed its Melbourne, Florida assembly complex into a high-margin cash generator.
Embraer’s surge is powered by two category killers:
The Phenom 300E: Remaining the world’s best-selling light jet for well over a decade, the single-pilot-certified, Mach 0.80 Phenom 300E is the backbone of fractional and corporate shuttle fleets across North America and Europe.
The Praetor 500 and Praetor 600: In the fiercely contested midsize and super-midsize arena, the Praetor 600 offers true intercontinental range (4,018 nm—capable of London to New York nonstop) and full fly-by-wire technology with active turbulence reduction at a price point that undercuts large-cabin competitors.
Bombardier’s $270 Million U.S. Expansion and Strategic Discipline
Across the border, Canadian rival Bombardier is playing a disciplined, high-margin game of its own. Having refocused entirely on business aviation, defense special-mission aircraft, and aftermarket services, Bombardier is supplementing its flagship Global 7500 (and upcoming Mach 0.94 Global 8000) and Challenger 3500 production with a $270 million investment to expand its U.S. operational footprint.
OEM | 2026 Backlog / Milestone | Core Flagship Platforms | Primary Production & Expansion Strategy |
Gulfstream Aerospace | $25.0 Billion Backlog | G700, G800, G600, G500, G280 | Scaling Savannah manufacturing and completions toward 200 jets/year |
Embraer Executive Jets | $8.2 Billion Backlog (Record) | Phenom 300E, Praetor 500, Praetor 600 | Expanding Melbourne, FL final assembly & sub-tier supplier vertical integration |
Bombardier | $270M U.S. Footprint Expansion | Global 7500/8000, Challenger 3500/650 | Growing U.S. MRO service centers, Wichita defense hub, and recurring aftermarket revenue |
Textron Aviation | 1,220+ Flight-Test Hours on Gen3 | Citation Ascend, CJ4 Gen3, CJ3 Gen3, M2 Gen3 | Certifying Garmin Emergency Autoland across Gen3 lineup for 2027 service entry |
Why is Bombardier channeling $270 million into its U.S. facilities (centered around Wichita, Kansas, Dallas, Miami, and new regional service hubs)?
Capturing Recurring Aftermarket MRO: An installed fleet of more than 5,000 Bombardier Learjet, Challenger, and Global aircraft flies predominantly in U.S. airspace. Expanding U.S. service center bay capacity captures high-margin heavy maintenance, Ka-band/Starlink connectivity retrofits, and interior refurbishments that carry 20%+ EBITDA margins regardless of new aircraft delivery cycles.
Defense Special-Mission Growth: Operating from its U.S. defense headquarters in Wichita, Bombardier is aggressively marketing the Global 6500 and Challenger 650 as the premier platforms for U.S. Army (HADES) and allied airborne intelligence, surveillance, and reconnaissance (ISR) programs, which require domestic U.S. modification and engineering facilities.
Can the Tier-2 and Tier-3 Supply Chain Hold Under a 200-Jet Ramp?
The central risk facing Gulfstream's 200-jet target and Embraer's $8.2B backlog burn-down is not customer cancellations—it is sub-tier supply chain fragility. While Tier-1 avionics and engine suppliers (Honeywell, Garmin, Collins Aerospace, Rolls-Royce, P&WC) have expanded capacity, bottlenecks persist in three critical areas:
Aerospace Castings and Forgings: High-tolerance titanium and nickel-superalloy structural forgings and landing gear assemblies remain constrained by skilled foundry labor and shared demand from commercial narrowbody ramps (Boeing 737 MAX and Airbus A320neo) and military programs (F-35, B-21).
Certified Cabin Interior Artisans & Actuators: Custom seat frames, electro-chromatic window shades, and acoustic insulation kits require specialized certification testing under FAA dynamic sled standards; a single delayed galley or divan mechanism can hold a $75 million jet in the completion hangar for weeks.
Skilled A&P Technicians: Competition between airlines, MRO facilities, and OEM assembly lines for FAA-licensed Airframe and Powerplant (A&P) mechanics remains fierce.
To prevent supply chain fractures from stalling deliveries in 2027, Gulfstream, Embraer, and Bombardier are increasingly embedding their own quality engineers inside Tier-2 suppliers, dual-sourcing critical machined components, and holding higher buffer inventories of long-lead raw materials—proving that in 2026, managing a $33 billion backlog is first and foremost a masterclass in industrial logistics.
5-Item Q&A Section
Q1: What is Gulfstream Aerospace’s current order backlog and production target in 2026? As of mid-2026, Gulfstream Aerospace holds a $25 billion order backlog and is actively scaling its manufacturing and completion operations to reach an annual production rate of 200 business jets per year.
Q2: How large is Embraer’s executive jet backlog in 2026?
Embraer Executive Jets has reached a record $8.2 billion backlog in 2026, driven by sustained fleet and corporate demand for its industry-leading Phenom 300E light jet and Praetor 500/600 midsize and super-midsize business jets.
Q3: How is Bombardier expanding its U.S. presence in 2026?
Bombardier is executing a $270 million U.S. footprint expansion focused on growing its domestic maintenance, repair, and overhaul (MRO) service center network, customer support infrastructure, and Wichita-based defense special-mission modification capabilities.
Q4: What are the biggest supply chain risks facing business jet manufacturers in 2026–2027?
As OEMs ramp production, the primary supply chain bottlenecks sit in Tier-2 and Tier-3 structural titanium/alloy castings and forgings, certified custom cabin interior components (seating and cabinetry), and a nationwide shortage of licensed A&P aviation technicians.
Q5: What progress has Textron Aviation made on its Citation Gen3 business jets?
Ahead of NBAA-BACE 2026, Textron Aviation announced that its three new Cessna Citation Gen3 light jets (Citation M2 Gen3, CJ3 Gen3, and CJ4 Gen3)—all equipped with Garmin Emergency Autoland—have surpassed 1,220 flight-test hours and remain on track for commercial service entry in 2027.
Keywords and Hashtags
Keywords: Gulfstream $25B backlog 200 deliveries, Embraer $8.2B executive jet backlog, Bombardier $270M US expansion, business aviation supply chain 2026, NBAA-BACE 2026 OEM outlook, Gulfstream G700 G800 production rate, Praetor 600 vs Challenger 3500.
Hashtags: #BusinessAviation #Gulfstream #Embraer #Bombardier #BizAv #NBAABACE #AerospaceSupplyChain #PrivateJets
