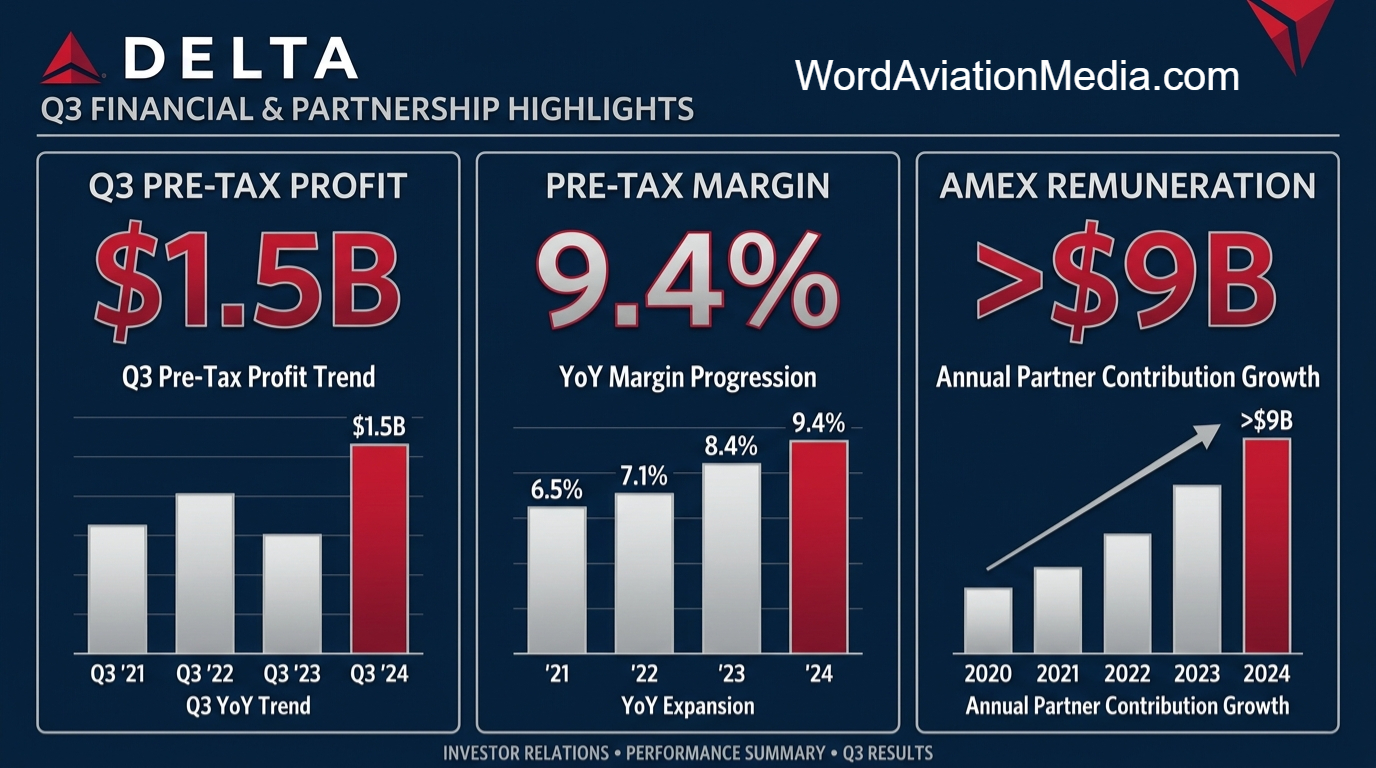
Delta Air Lines Q3 2026 Financial Results: $1.5B Pre-Tax Profit, $17.59B Adjusted Revenue, and $9B+ AmEx Ecosystem Anchor Full-Year Outlook
Key Takeaways
Industry-Leading Profitability: Delta Air Lines delivered Q3 2026 pre-tax profit of $1.5 billion, adjusted diluted EPS of $1.72, a 9.4% operating margin, and an 11% return on invested capital (ROIC) on $17.59 billion in adjusted revenue (+16% YoY).
Massive Cash Flow & Deleveraging: Year-to-date free cash flow reached $1.9 billion through Q3, keeping Delta firmly on track for full-year 2026 free cash flow of ~$2.5 billion and more than $2.0 billion in total debt reduction.
American Express Loyalty Juggernaut: Delta confirmed that full-year 2026 remuneration from its co-branded American Express partnership will exceed $9.0 billion, advancing steadily toward its long-term $10 billion annual target.
Resilient Full-Year 2026 Guidance: Management projected full-year 2026 pre-tax income of approximately $4.5 billion and full-year adjusted EPS of $5.10 to $5.60, demonstrating structural insulation against late-2026 fuel volatility.
Quality of Revenue Over Volume: While Q3 adjusted EPS ($1.72) and adjusted revenue ($17.59 billion) came in slightly below initial pre-fuel-spike Wall Street consensus, Delta’s 9.4% operating margin outpaced all North American peers by a wide margin.
How Did Delta Air Lines Lead the Industry in Q3 2026 Profitability?
Delta Air Lines, Inc. (NYSE: DAL) once again demonstrated why its financial profile resembles a high-margin consumer brand and industrial powerhouse rather than a cyclical commodity airline. In the third quarter of fiscal year 2026, Delta generated $17.59 billion in adjusted operating revenue, representing a 16.0% year-over-year increase. Pre-tax income held firm at $1.5 billion, translating into adjusted diluted earnings per share of $1.72 and an industry-best 9.4% operating margin.
While the late-summer spike in jet fuel prices caused Delta’s $1.72 adjusted EPS and $17.59 billion adjusted revenue to fall slightly short of Wall Street’s pre-spike consensus estimates (prompting a mid-quarter fuel outlook adjustment), Delta’s absolute profit generation towered over the sector. Over the trailing twelve months through Q3 2026, Delta maintained an 11% Return on Invested Capital (ROIC) and accumulated $1.9 billion in year-to-date free cash flow.
Financial Metric & Guidance Benchmark | Q3 2026 Actual | Full-Year 2026 Outlook / Target |
Adjusted Operating Revenue | $17.59 Billion (+16.0% YoY) | Sustained Double-Digit Revenue Quality |
Pre-Tax Profit | $1.5 Billion | ~$4.5 Billion Full-Year Pre-Tax Profit |
Adjusted Diluted EPS | $1.72 | $5.10 – $5.60 Full-Year Adjusted EPS |
Operating Margin | 9.4% | Industry-Leading Margin Profile |
Return on Invested Capital (ROIC) | 11.0% | Double-Digit ROIC Target Met |
Free Cash Flow (FCF) | $1.9 Billion (YTD Q3) | ~$2.5 Billion Full-Year 2026 FCF |
Balance Sheet Debt Reduction | Active Deleveraging | >$2.0 Billion Debt Reduction in FY2026 |
AmEx Co-Brand Remuneration | High-Teens Growth Pace | >$9.0 Billion in FY2026 (Path to $10B) |
Why Does Delta Outperform Peers During Fuel Price Spikes?
When jet fuel prices surged past $3.90 per gallon in Q3 2026, most North American carriers saw their operating margins compressed to the low single digits or into negative territory (Southwest posted a 5.4% adjusted operating margin; United posted a 6.2% pre-tax margin; American and JetBlue posted net losses). Delta’s ability to defend a 9.4% operating margin and $1.5 billion in quarterly pre-tax profit rests on three structural pillars:
1. The $9 Billion+ American Express SkyMiles Ecosystem
Delta’s co-branded credit card partnership with American Express is the single most lucrative loyalty agreement in global aviation. During its Q3 2026 financial review, management confirmed that annual cash remuneration from American Express will exceed $9.0 billion in full-year 2026, keeping the airline firmly on its trajectory toward a $10 billion annual run-rate. Because co-brand loyalty cash flows carry operating margins north of 50% and are tied to affluent consumer retail spend rather than jet fuel consumption, this $9B+ revenue stream provides a massive structural buffer against energy volatility.
2. Premium Cabin Mix and Coastal Core Hub Dominance
More than 55% of Delta’s total revenue is derived from premium seating (Delta One, Delta Premium Select, First Class, and Comfort+), loyalty remuneration, cargo, and third-party Maintenance, Repair, and Overhaul (MRO) services via Delta TechOps. Combined with fortress interior hubs in Atlanta, Minneapolis-St. Paul, Detroit, and Salt Lake City, plus premier coastal positions in New York (JFK/LGA), Boston, Seattle, and Los Angeles, Delta commands an industry-leading yield premium that absorbs fuel cost pass-throughs with minimal load factor degradation.
3. Monroe Energy Trainer Refinery Hedge
Unlike its U.S. airline peers, Delta owns and operates the Monroe Energy refinery in Trainer, Pennsylvania. During periods when crude oil rises and refined jet fuel crack spreads widen—as occurred in late Q3 and early Q4 2026—the Trainer refinery captures refining margins that partially offset the higher cost of jet fuel at the wingtip.
Balance Sheet Fortification and Full-Year 2026 Guidance
While high-leverage competitors like American Airlines and WestJet have been forced to pause net debt reduction in late 2026 due to fuel expenses, Delta’s cash generation remains robust. Having generated $1.9 billion in year-to-date free cash flow through the end of Q3, Delta guided full-year 2026 free cash flow to approximately $2.5 billion—meaning the airline expects to generate roughly $600 million in positive free cash flow during the fourth quarter alone, despite Q4 industry fuel headwinds.
Management reaffirmed its commitment to reducing total debt by more than $2.0 billion in full-year 2026, further strengthening its investment-grade credit ratings (BBB- / Positive at Fitch). For the full fiscal year 2026, Delta projects:
Full-Year Pre-Tax Income: ~$4.5 billion
Full-Year Adjusted EPS: $5.10 to $5.60 per diluted share
By combining strict domestic capacity discipline with ongoing fleet upgauging to fuel-efficient Airbus A321neos, A220-300s, and A350-900/1000 widebodies, Delta continues to widen the financial moat separating it from the broader aviation sector.
5-Item Q&A Section (FAQ)
Q1: What were Delta Air Lines' Q3 2026 EPS, revenue, and pre-tax profit?
In Q3 2026, Delta Air Lines reported adjusted diluted EPS of $1.72, pre-tax profit of $1.5 billion, and adjusted operating revenue of $17.59 billion (+16% YoY), achieving a 9.4% operating margin and 11% ROIC.
Q2: What is Delta Air Lines' full-year 2026 EPS and free cash flow guidance?
Delta guided full-year 2026 adjusted EPS to a range of $5.10 to $5.60 on approximately $4.5 billion in full-year pre-tax profit. Full-year free cash flow is projected at ~$2.5 billion (up from $1.9 billion YTD through Q3), enabling more than $2.0 billion in debt reduction in 2026.
Q3: How much revenue does Delta generate from its American Express partnership in 2026?
Delta confirmed that full-year 2026 remuneration from American Express will exceed $9.0 billion, keeping the carrier on pace to reach its $10 billion annual co-brand remuneration target.
Q4: Why did Delta adjust its Q3 2026 outlook relative to initial Wall Street consensus?
While top-line revenue rose 16% to $17.59 billion, a late-quarter surge in jet fuel costs across North America trimmed Q3 adjusted EPS to $1.72, slightly below pre-fuel-spike Wall Street expectations, though Delta still maintained an industry-leading 9.4% margin.
Q5: How does Delta's Q3 2026 operating margin compare to its U.S. airline peers?
Delta's 9.4% Q3 2026 operating margin led all major U.S. carriers, outperforming United Airlines (6.2% pre-tax margin), Southwest Airlines (5.4% adjusted operating margin), and American Airlines and JetBlue (which both posted Q3 net losses).
Metadata
Target SEO Keywords: Delta Air Lines Q3 2026 financial results, DAL Q3 2026 earnings report, Delta $1.5B pre-tax profit, Delta American Express $9 billion remuneration 2026, DAL stock free cash flow 2026, Delta Air Lines 9.4% operating margin, Ed Bastian Q3 2026 earnings call.
Hashtags: #DeltaAirLines #DALStock #AirlineEarnings #Q32026Results #SkyMiles #AmExPartnership #AviationFinance
